Banco BPM Jumps 10% on Crédit Agricole Merger Proposal as European Banks Lead a Cautious Rebound
A proposed combination of Crédit Agricole's Italian arm with Banco BPM and a strong UniCredit quarter lifted euro-zone banks on Monday, while cheaper oil and a tentative recovery in global stocks set the tone before U.S. inflation data.
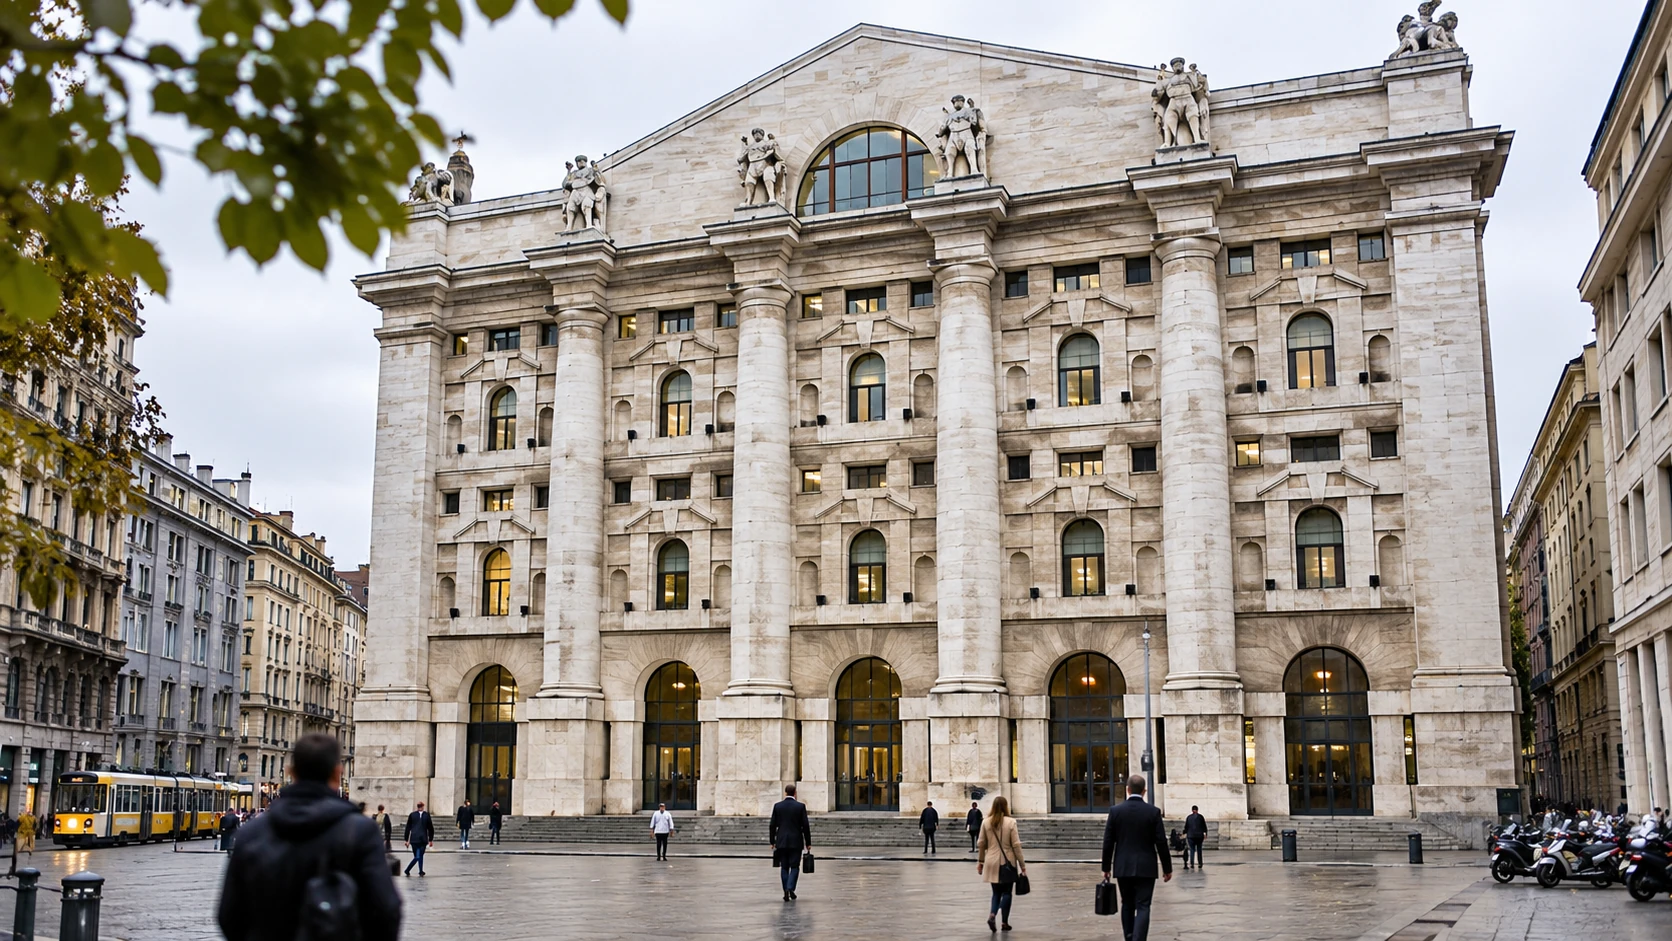
Shares in Italy's Banco BPM rose about 10% on Monday, November 9, after French lender Crédit Agricole proposed merging its Italian subsidiary with the bank, according to Reuters reporting carried by Investing.com. The combined group would become Italy's third-largest bank by that account. Crédit Agricole's own shares fell about 1%. The move helped the Euro STOXX banking index gain 1.6% in a session where the wider market was only modestly higher.
The proposal
Crédit Agricole has now published the proposed terms. Its plan would combine Banco BPM with Crédit Agricole Italia, retain a Milan listing and create Italy's third-largest banking group, with approximately 6.5 million customers and more than 2,300 branches. The French lender currently holds 29.6% of Banco BPM and estimates it would own about 45% of the combined entity. The proposal is friendly, but Banco BPM's board has only been asked to evaluate it; the banks have not announced a signed merger agreement.
Under the published proposal, Banco BPM shareholders would receive a share-exchange ratio reflecting a 20% valuation premium, plus a €1 billion extraordinary dividend. Crédit Agricole projects €800 million of annual pre-tax synergies and an approximately 24% increase in Banco BPM earnings per share in 2027. Importantly, the stated premium is defined by a comparison of projected 2027 price-to-earnings multiples, rather than simply a 20% cash premium over the last market close. The transaction would require shareholder and regulatory approvals, including European Central Bank authorization and Italian golden-power review. Crédit Agricole says completion could come in the second half of 2027. These are proposal terms and forecasts, not realized benefits.
UniCredit's quarter
UniCredit gained 5.2% after its third-quarter earnings rose 24% from a year earlier and it raised its full-year profit target, according to Reuters via Investing.com. The same report says the bank is preparing to shape strategy at Commerzbank, whose shares rose 2.8%. Those two stories together explain why banks, and not technology shares, led the European session.
Other European moves were smaller. SAP rose about 2% after a J.P. Morgan upgrade to overweight. Hochtief fell about 4% after its majority shareholder ACS said it had not considered a takeover bid. LVMH and Christian Dior each fell more than 2% after weak October consumer data from China.
A pan-European index that barely moved
The STOXX 600 rose 0.5% to 651.38 points in a snapshot taken at 09:26 GMT, according to Reuters. Chip-equipment names such as Aixtron and ASML swung between small gains and losses after sharp declines the previous week, which the report tied to concerns about the AI trade after Democrats won control of Congress, as covered in our Asia and Europe selloff report.
Global shares recovered some ground. MSCI's World index rose 0.5% from six-month lows, and its Asia-Pacific index excluding Japan rose 1.25% after falling 4.6% the previous week, according to Reuters via MarketScreener. Taiwan's benchmark gained almost 5%, a move examined in our Asia rebound report.
Oil and rates
Brent crude fell about 3% to $95 a barrel and U.S. West Texas Intermediate dropped almost 3% to about $88.37 as diplomacy to end the Iran war gained pace, according to Reuters via MarketScreener. Earlier in the morning, a TipRanks update put Brent at $97.64, down 0.69%, and WTI at $90.48. The two quotes reflect different times, and Brent was moving quickly after President Donald Trump told CNN that further strikes on Iran were "highly unlikely" while talks continue. The background to the blockade is in our weekend oil analysis.
The 10-year U.S. Treasury yield was 4.84% and the dollar index slipped 0.4% to 101.81, according to the same Reuters report. Traders priced about an 80% chance of a quarter-point Federal Reserve hike in December after the October jobs report. U.S. October consumer prices are due Tuesday at 8:30 a.m. Eastern time, and this week's earnings include CoreWeave, Applied Materials and Cisco.
Wall Street's early signals
U.S. stock index futures pointed higher before the open. At 5:30 a.m. Eastern time, Dow futures were up 0.79%, S&P 500 futures up 0.47% and Nasdaq 100 futures up 0.29%, according to a TipRanks update stamped 10:33 UTC. Nvidia fell just over 4% in premarket trading after announcing an internal investigation involving its chief executive, as covered in our technology report. Futures move during the session and may differ from the later close.
ECB expectations
Investors expect the European Central Bank to raise rates by at least 25 basis points in February, according to Reuters via Investing.com. Attention this week is on euro-zone October inflation and third-quarter growth data, as well as the question of who will succeed Christine Lagarde as ECB president. Higher policy rates generally support bank net interest income, which is one reason banks have outperformed in rate-hike scenarios, though funding costs and credit quality also matter.
What the evidence supports
The evidence supports a narrow conclusion. Banks rose on specific corporate news, not on a broad change in sentiment. The proposal for Banco BPM is a transaction story, and UniCredit's gain is an earnings story. Oil's decline and the global stock rebound are separate developments that may or may not hold. The reports do not show that investors have decided the AI-related selloff is over.
What to watch
The first marker is Banco BPM’s formal response to Crédit Agricole’s published proposal and the reaction of regulators to the ownership structure. The second is Tuesday's U.S. consumer price report and its effect on the December hike odds. The third is whether Brent holds below $100 as talks continue. The fourth is whether Nvidia's premarket decline extends into the U.S. session.
Limits of the reporting
The merger proposal and its headline financial terms have been checked against Crédit Agricole’s official announcement, but a binding agreement has not been disclosed. Prices come from snapshots at different times, so index levels and oil prices differ between sources. Several sources are Reuters stories republished by aggregators, which count as one source and not several.