Calls, Puts and the Price of an Option
The contract's right, premium and expiry explain its payoff. The risks differ sharply between a buyer and a seller.
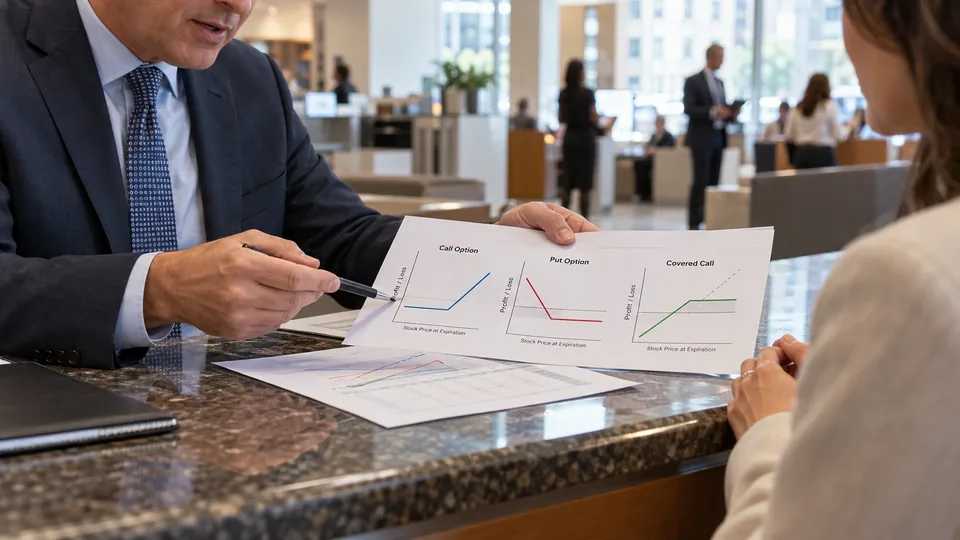
An option separates the right to make a transaction from the obligation to make it. A call gives its buyer the right to buy an underlying security at a specified strike price; a put gives the right to sell. The premium buys that contractual right for a limited period, rather than ownership of the underlying shares.
The distinction explains why correctly forecasting a stock's direction may still produce an option loss. The size of the move, the time available and the premium paid all matter. A contract can gain intrinsic value yet fail to recover its original cost.
Start with the contract rather than the headline price
A standard listed US equity option generally represents 100 shares, although corporate actions can create adjusted contracts with different deliverables. A premium quoted at $3 therefore usually costs $300 for one contract. Strike, expiration, multiplier and settlement terms belong in any calculation before a position is compared with buying shares.
American-style options can be exercised before expiration; European-style exercise occurs only at expiration. These labels describe contract terms rather than the investor's location. A holder can also sell an option to close a position instead of exercising, subject to a market being available at an acceptable price.
The seller receives the premium but accepts an obligation if assigned. That obligation is different from the buyer's right. The fact that a purchased option has limited initial downside does not make every strategy involving options limited-risk.
A call example separates value from profit
Suppose a hypothetical stock trades at $50 and an investor buys one call with a $55 strike for a $3 premium. At expiration, a $60 share price gives the call $5 per share of intrinsic value. For a standard 100-share contract, that is $500 against the $300 premium, leaving a $200 profit before costs.
If the stock instead finishes at $56, the call has $100 of intrinsic value but the position loses $200 after the premium. The share price rose, and the option finished in the money, yet the buyer lost. The expiration breakeven is $58: the strike plus the premium.
At $55 or below, the call has no intrinsic value at expiration and the $300 premium can be lost entirely. These are expiration calculations. Before expiration, an option's market price may include time value, so the same share price need not produce the same sale proceeds.
A put works in the other direction
Now suppose a hypothetical investor pays $2 per share for a $45-strike put. If the stock ends at $40, the put has $5 per share of intrinsic value. Subtracting the premium gives $3 per share, or $300 on a standard contract, before costs. The expiration breakeven is $43.
A shareholder can use a put to limit downside over its term, but the protection has a cost and an end date. Pairing 100 shares bought at $50 with that put costs $5,200 before fees. Exercise at $45 would return $4,500, producing a $700 combined loss. Calling the stock protected does not mean its purchase price is guaranteed.
These examples deliberately exclude dividends, financing, taxes and transaction costs. Those items can matter in practice. A payoff diagram is a description under stated assumptions, not a complete estimate of the economics for every account.
Time and volatility affect the premium
An option's price reflects more than the distance between the share price and strike. Remaining time and implied volatility affect the value of possible future outcomes. Other things equal, the passage of time generally reduces an option's time value, although the actual price can rise when other inputs change.
Before a major announcement, investors may pay a substantial premium for uncertainty. After the announcement, implied volatility can fall. A modest favorable share-price move may then be outweighed by the reduction in time value. This is one reason an earnings beat need not make a call profitable.
Selling options creates a different set of risks
An uncovered call seller can face theoretically unlimited losses because the stock has no fixed upper price. A put seller can face a large loss if the underlying approaches zero. A covered call has stock downside and limits upside; the premium does not remove the equity exposure.
Contract liquidity and the bid-ask spread also affect execution. Comparing a last-traded price with an immediately executable bid can overstate a position's value. Read options alongside implied volatility, but evaluate the actual contract, its obligations and the whole position before interpreting a quoted premium as inexpensive.
Sources and methodology (2)
Primary references for the definitions, methods and risks discussed above. Examples labeled hypothetical or illustrative are not current market quotations.
TTN analysis for informational purposes. This article is not investment, tax or legal advice.